Late pension split: mail by Nov 302023 pension split closes December 31, 2027Medicare drug-plan window closes Dec 7The Home Front Manual · 2026–2027 Edition
Gord Wallace

As shown in the video

After a lifetime of looking after everyone else, take a closer look at what you’ve built.

Same bank. Same accounts. The same way, every April. How much is that loyalty quietly costing you? For one retired Ontario couple in our book, it came to C$7,043 over 12 months.

Show me where it’s hiding ↓ Or get the Manual now · C$47 →

Large print · Print it at home · If it isn’t right for you, every penny back

Gord Wallace

As shown in the video

After a lifetime of looking after everyone else, take a closer look at what you’ve built.

Same insurer. Same plans. The same way, every year. How much is that loyalty quietly costing you? For one retired Maryland couple in our book, it came to $6,942$5,742 over 12 months.

Show me where it’s hiding ↓ Or get the Manual now · $47 →

Large print · Print it at home · If it isn’t right for you, every penny back

As shown in the video

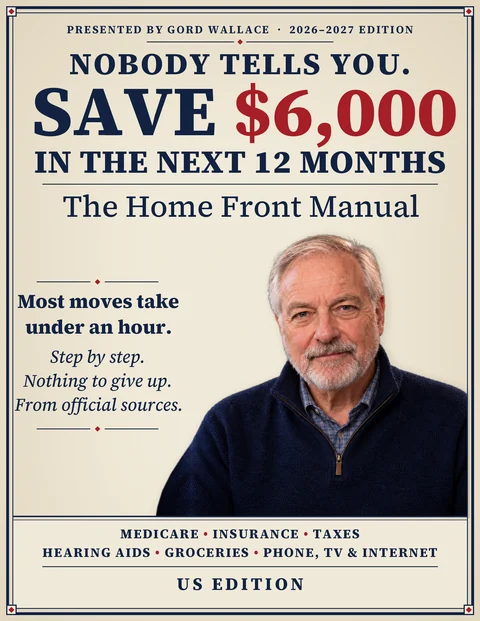
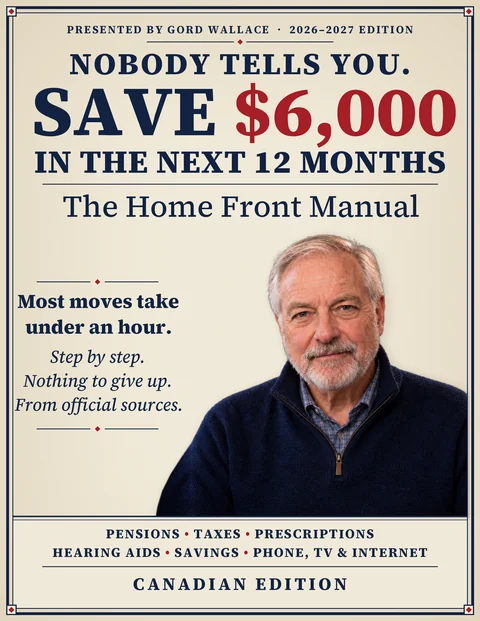
Nobody tells you. SAVE $6,000$6,000$5,000 in the next 12 months

I.

The loyalty tax

Loyal for decades. Charged for it.

Nobody sends a letter. Nobody calls. The companies we stayed loyal to often charge loyal customers more than new ones, and the government’s own rules leave money waiting for couples who never ask. Here is where it was hiding for our example couple: retired in Ontario, both 68.

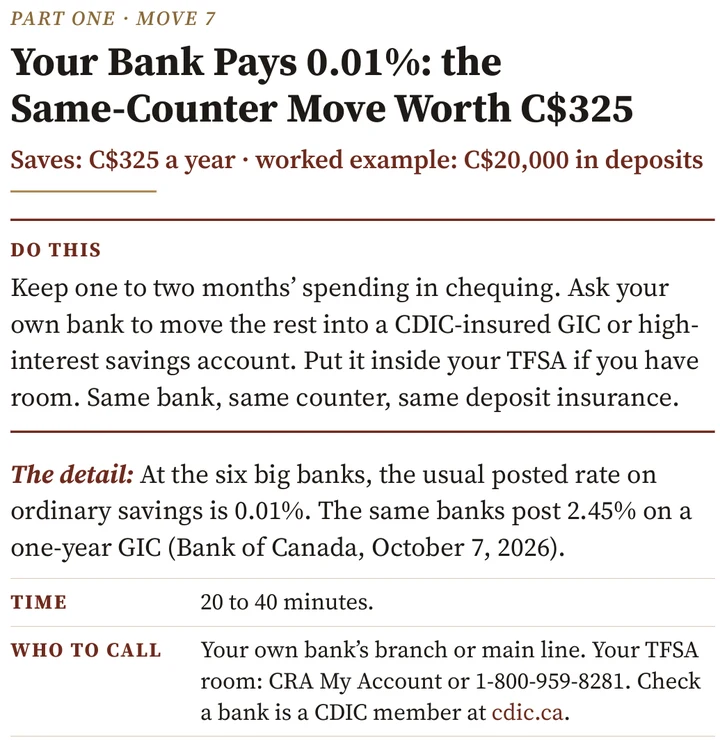
  • Loyal to your bank. Ordinary savings at the six big banks earn 0.01%. The same banks post 2.45% on a one-year GIC, at the same counter, with the same deposit insurance. Twenty thousand dollars at 0.01% earns two dollars a year. A GIC locks the money for the year, so the book shows how much to keep in chequing first.C$325 a yearBank of Canada posted rates, week of October 28, 2026
  • Loyal to your phone company. Every big network sells a cheaper second brand that runs on the very same towers. Virgin Plus on Bell. Fido on Rogers. Koodo on Telus.C$264 a year · two lines
  • Loyal to your internet company. Its own website often sells your same speed for less than you pay. The call to ask for it is written out in the book.C$240 a year
  • Loyal to your TV package. Federal rules require the big TV providers to offer a basic package of no more than C$25 a month, before equipment. Ask for it by name.C$167 a year
  • Loyal to the way you’ve always filed. One pension on one return, every April. Married couples can split it, and can ask the CRA to go back three years.C$3,190 once · then C$1,182 every year · the CRA decides
  • Loyal to “we’ll manage.” Medical bills on the right spouse’s return. Ontario’s help toward hearing aids, up to C$1,000 if you buy in the right order. The 100-day prescription fill. The C$100 drug deductible your retiree plan may pay back.C$1,675 for our example couple

For our example couple: C$7,043 in the next 12 months. Same bank, same doctor, same channels. They didn’t give anything up. They asked.

How to stop paying it ↓

I.

The loyalty tax

Loyal for decades. Charged for it.

Nobody sends a letter. Nobody calls. The companies we stayed loyal to often charge loyal customers more than new ones, and the rules leave money waiting for people who never ask. Here is where it was hiding for our example couple: retired in Maryland, both 68, on Original Medicare.

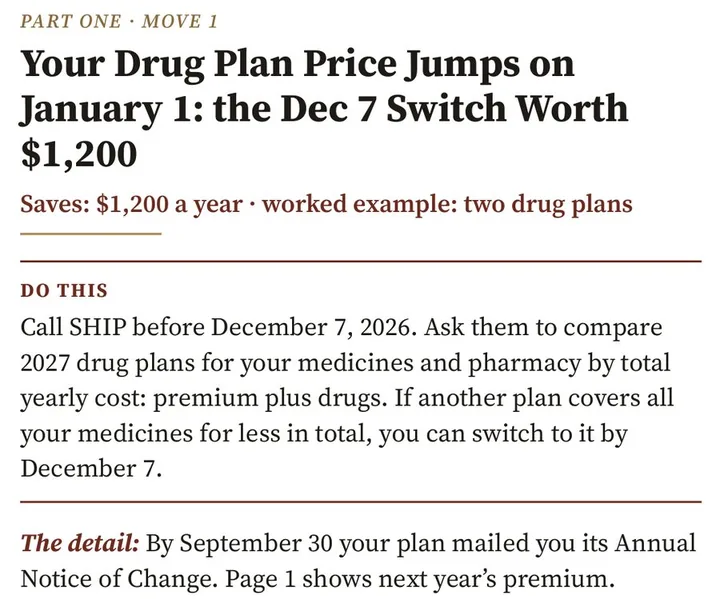
  • Loyal to your drug plan. A letter that arrived by September 30 shows whether your Medicare drug plan costs more on January 1. Most of us put it in a drawer. The window to switch closes December 7.$1,200 a year
  • Loyal to your Medigap policy. A 30-day window opens on your birthday. In Maryland it lets you keep the exact same Medigap coverage for less, with no health questions.$353 a year
  • Loyal to your insurers. Years with one car insurer can cost more than a new customer pays. And the state’s own price list shows one insurer charging 5.6 times another for the identical home policy.$861 a year · car and home
  • Loyal to your phone company. Same phones, same towers, a lower plan.$350 a year
  • Loyal to your cable and internet bill. The “Broadcast TV fee” looks like a tax but isn’t. And the FCC price label shows what your internet plan really costs, next to the plans you could have instead.$420 a year
  • Loyal to “we’ll manage.” Since 2022, adults can buy hearing aids off the shelf, without the clinic price. Free tax filing aimed at people 60 and older. The property-tax cap you have to apply for. The same brands, a third cheaper. The warranty rule that says routine service elsewhere can’t void it.$3,758 for our example couple

For our example couple: $6,942$5,742 in the next 12 months. Same doctors, same coverage, same channels. They didn’t give anything up. They asked.

How to stop paying it ↓

I.

The Manual

Every place the loyalty tax hides, and exactly what to say to stop paying it.

Part One: stop paying the loyalty tax. Twelve moves: your drug plan, Medigap, hearing aids, car and home insurance, your phone, cable and internet, taxes, the property-tax cap, the brands you buy and your warranty.Part One: stop paying the loyalty tax. Ten moves: your bank, your phone, your internet, your TV, the pension split, medical bills, hearing aids and prescriptions.

Part Two: protect what you’ve built. Eleven moves: how a couple can keep $500,000 at one bank fully insured, the beneficiary form that overrides your will, the free credit freeze, the family code word, and more.

Part Two: protect what you’ve built. Eleven moves: the C$100,000 line at your bank, the beneficiary form that overrides your will, freezing your credit, the family code word, and more.

You don’t switch plans or give anything up. You ask, using the exact words in the book.You don’t switch banks or give anything up. You ask, using the exact words in the book.

The Home Front Manual, US Edition, presented by Gord Wallace.
The Home Front Manual, Canadian Edition, presented by Gord Wallace.

Large-print ebook · 140 pages · 2026–2027 EditionLarge-print ebook · 133 pages · 2026–2027 Edition

Written for a retired American household. Large print. Print it at home.Written for a retired Canadian household. Large print. Print it at home.

Every figure checked against official sources in October 2026, with the source printed beside it.

What’s inside:

  • The Home Front Manual — 140-page large-print ebook, 23 numbered moves: 12 to save, 11 to protect what you keep133-page large-print ebook, 21 numbered moves: 10 to save, 11 to protect what you keep, in Canadian dollars
  • For every move — the official rule, the deadline, who to call, the exact words to say, the line for when they push back, the catch, and a page to write down who you spoke to
  • Start Here — the first calls to make this week
  • The 20-Minute Worksheet, every phone script on one page and the Deadline Calendar
  • The Family Workbook — 20 fillable pages: medication lists, accounts map, emergency plan and the Fridge Sheet
  • Free updates — every figure checked against official sources in October 2026; the January 2027 refresh comes at no extra charge
  • One payment$47
Get the Manual · $47 →

Instant access · Pay once · Yours forever

Secure checkout · Visa · Mastercard · Apple Pay · Google Pay · 30-day refund

Not a summary. The real thing.

Every move is written out, word for word.

Move 1, US Edition, as printed in the book.
Move 7, Canadian Edition, as printed: Your Bank Pays 0.01%.

Move 7, your bank, exactly as printed. Tap the page to read it full size.

And on the next page, the exact words to say at the counter: “I have about ____ in my savings account. What rate is it earning today, exactly?” Plus what to say when they offer you something else.

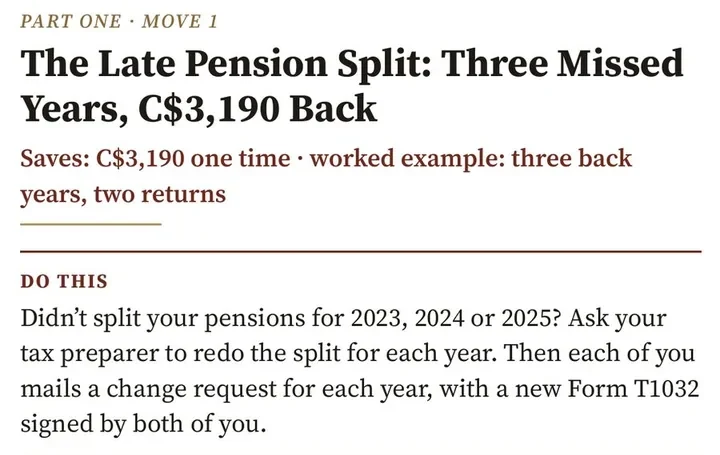
Move 1, Canadian Edition, as printed: The Late Pension Split.

Move 1, the late pension split. The CRA decides whether to accept it.

Move 1, exactly as printed. Tap the page to read it full size.

  • The official rule and the deadline
  • Who to call, and the exact words to say
  • The line for when they push back
  • The catch, and a page to write down who you spoke to

Check it yourself on canada.ca: Form T1032 · Form T1-ADJ. Every figure in the manual names its official source, checked October 2026.

Every figure in the manual names its official source, checked October 2026.

II.

The Math

One worked example. Every line shown.

Pull up your last 12 months of bills and follow along. Our example couple: retired in Maryland, both 68, on Original Medicare. It’s one household, not a promise or an average. Yours will be different.Our example couple: retired in Ontario, both 68, one of them with most of the workplace pension. It’s one household, not a promise or an average. Yours will be different. Every line comes straight from the manual’s Ledger.

  • The December 7 drug-plan windowEvery year$1,200
  • The Medigap birthday windowEvery year$353
  • The 2022 hearing-aid ruleOne time · one pair$2,820
  • The car-insurance new-customer re-rateEvery year$461
  • The state’s own home-insurance price listEvery year$400
  • Same phones, same towers, lower planEvery year$350
  • The cable fees that aren’t taxesEvery year$240
  • The FCC internet price labelEvery year$180
  • Free tax filing at 60+Every year$220
  • The property-tax cap you apply forYear one$115
  • Same brands, a third cheaperEvery year$421
  • The federal warranty ruleEvery year$182
  • The next 12 months$6,942
  • The next 12 months$5,742
  • The late pension split, 2023–2025One time · the CRA decidesC$3,190
  • Pension splitting every yearEvery yearC$1,182
  • Medical bills on the right returnEvery yearC$265
  • Ontario’s hearing-aid helpOne timeC$1,000
  • The 100-day prescription fillEvery yearC$210
  • Your drug deductible, paid backEvery yearC$200
  • Savings off 0.01%, same bankEvery yearC$325
  • Same network, cheaper brandEvery yearC$264
  • The internet price already advertisedEvery yearC$240
  • The C$25 TV packageEvery yearC$167
  • The next 12 monthsC$7,043
$4,122$2,922is kept every year, year after year
$2,820is one time: hearing aids off the shelf, one pair
C$2,853is kept every year, year after year
C$4,190is one time: the late split (the CRA decides) and the hearing-aid help
C$2,671is what the same couple keeps without the two pension-split moves, in the same 12 months

Every number has a move in the Manual, with the official source and the steps.

$6,942$5,742C$7,043The first 12 months
vs
$47The Manual, once
Get the Manual · $47 →

Instant access · Pay once · Yours forever

Our worked example

Forty-one years at the same branch.

Doug and Carol banked at the same branch in Oshawa for forty-one years. Same savings account. Same phone company since the kids were small. Every April, their returns went in the same way they always had. They paid every bill on time. They thought loyalty counted for something.

Then one evening, at the kitchen table, they finally checked. Their savings were earning two dollars a year on twenty thousand. Their phone company’s own cheaper brand ran on the same towers. And the pension they’d filed on one return for years could have been split, back three years.

Nobody had told them. Not the bank. Not the phone company. Not the tax people. They hadn’t been careless. They’d been loyal.

They didn’t change banks or doctors, or give anything up. They asked. And over the next twelve months, it came to C$7,043.

Doug and Carol are the worked example couple in our Manual. Your number will be different.

You spent a lifetime looking after everyone else. This is about looking after what you’ve built, and making sure that if one of you is ever on your own, nothing is left to guess.

Our worked example

Thirty years with the same insurer.

Bill and Karen, retired in Dundalk, Maryland, kept the same car insurer for thirty years. The same cable package since the kids were small. Every fall, the drug-plan letter went into the kitchen drawer unopened. They paid every bill on time. They thought loyalty counted for something.

Then one evening, at the kitchen table, they finally checked. The letter showed their drug plan was about to cost more next year. Their insurer was charging them more than it charged new customers. And the hearing aids Bill had put off for years were sold off the shelf, without the clinic price.

Nobody had told them. Not the insurer. Not the cable company. Not the plan. They hadn’t been careless. They’d been loyal.

They didn’t change doctors or give anything up. They asked. And over the next twelve months, it came to $6,942$5,742.

Bill and Karen are the worked example couple in our Manual. Your number will be different.

You spent a lifetime looking after everyone else. This is about looking after what you’ve built, and making sure that if one of you is ever on your own, nothing is left to guess.

Start where you are

Which household is yours?

Tap yours. It shows where you start in the manual, and what the same moves were worth to our worked example.

Married, and one of us gets most of the pension Start at Move 1, the late pension split. Our example couple: C$3,190 back once (the CRA decides), then C$1,182 every year.
Say first · Move 1, page 27
“We didn’t split our pension income for 2023, 2024 or 2025. Please redo each year with the best split on Form T1032. We will both sign.”

Mail it by November 30 so all three years can come back within 12 months. The CRA decides whether to accept it.

The 2023 split must reach the CRA by December 31, 2027. The CRA decides whether to accept it.

Married, and our pensions are about even Start at Move 7, your savings rate. Without the two split moves, our example couple still keeps C$2,671 in 12 months, about C$101 a month from the five quickest moves.
Say first · Move 7, page 54
“I have about ____ in my savings account. What rate is it earning today, exactly?”

At the six big banks, the usual posted rate on ordinary savings is 0.01%. The same banks post 2.45% on a one-year GIC.

I live alone Start at Move 7. Your phone line, internet and TV package alone: about C$539 a year at our example’s prices. Plus your own savings rate, and in Ontario up to C$1,000 toward hearing aids.
How your number is worked out

One phone line: (C$51 − C$40) × 12 = C$132. Internet: C$240 and the TV package: C$167, because those bills are per home. Every Save move has a “Live alone?” line with the one-person figure.

Moves 1 to 3 need a spouse or partner, so you skip them.

We’re a married couple Start this week with Move 1, the drug-plan letter already in your mailbox (act by December 7). Our example couple: $6,942$5,742 in 12 months, about $99 a month from four quick bills.
The first month

Same phones, same towers, lower plan: $29 a month. The cable fees that aren’t taxes: $20. The FCC internet price label: $15. Same brands, a third cheaper: $35.

I live alone Every Save move shows the one-person figure. Bills charged per home are the same as a couple’s: $240 in cable fees, $180 on internet, the $115 property-tax cap.
A few one-person numbers

One phone line: $175 a year. Hearing aids: the same $2,820 on one pair. Your drug plan: $600 a year.

The first month

The four quickest moves, as a monthly figure.The five quickest moves, as a monthly figure.

  • Same phones, same towers, lower plan$29/mo
  • The cable fees that aren’t taxes$20/mo
  • The FCC internet price label$15/mo
  • Same brands, a third cheaper$35/mo
  • Every month$99
  • Savings off 0.01%, same bankC$27/mo
  • Same network, cheaper brandC$22/mo
  • The internet price already advertisedC$20/mo
  • The C$25 TV packageC$14/mo
  • The 100-day prescription fillC$18/mo
  • Every monthC$101

For our example couple, these four yearly amounts work out to about $99 a month: more than twice the price of the Manual, every month. When each one starts depends on your bills and your providers.For our example couple, these five yearly amounts work out to about C$101 a month: more than twice the price of the Manual, every month. When each one starts depends on your bills and your providers.

The Guarantee

$47, one payment. If it isn’t right for you, you get every penny back.

Use the manual for 30 days. If it isn’t right for you, for any reason at all, email [email protected] from the email you paid with, and you get every penny back. No reason needed. No questions asked.

What happens after you pay

  1. The secure checkout is right on this page. It shows C$47, tax included. It shows $47, tax included. It asks for your billing address, a bank rule for card payments.
  2. A download button appears right away, and an email with your link follows within minutes. Keep that email.
  3. Open Start Here: the three calls to make this week. Print it at home, or read it on any screen.

Can’t find it, or stuck on a step? Write to [email protected]. A person answers.

You don’t have to switch banks, or give anything up. You just have to ask.You don’t have to switch plans, or give anything up. You just have to ask.

Same bank. Same doctor. Same channels. The Manual gives you the exact words, and what to say when they push back.Same doctors. Same coverage. Same channels. The Manual gives you the exact words, and what to say when they push back.

Be the one in your house who has it on paper.

Get the Manual · $47 →

If it isn’t right for you, every penny back.

V.

Is it for you?

Who it’s for. And who it isn’t.

It’s for you if

  • you’re 65 or older, or close to it
  • you get CPP or OAS, or a workplace pension
  • you pay a phone, internet or TV bill
  • you keep savings at one of the big banks
  • and most of all: you’re married or common-law, and one of you gets most of the pension

It’s worth less to you if

  • you live alone: Moves 1 to 3 need a spouse or partner, so you start at Move 7
  • you already split your pensions every year
  • you live in Quebec: the provincial tax side works differently (the federal moves still apply)

Not sure? Buy it, fill in the 20-minute worksheet, and if it isn’t right for your household, email us within 30 days for every penny back.

Straight answers

Before you ask.

Why $47, when other guides cost $17 to $27?
Because it’s built to pay you back many times over: our worked example couple kept C$7,043$6,942$5,742 in 12 months. Free advice tells you a program exists. This gives you 2123 moves with the form, the deadline, who to call and the exact words to say. If it isn’t right for you, you get every penny back.
Do I have to switch plans or insurers?
No. Most moves are a question to the company you already use. You keep what you have and stop overpaying for it.
I’m on Medicare Advantage. Is this for me?
Yes. The manual shows Advantage members how to get the same free total-cost check on their plan, and most of the money moves have nothing to do with your Medicare plan at all: insurance, taxes, phones, TV, internet, groceries and car service.
Do I have to switch banks?
No. Most moves are a question to the company you already use: same bank, same phone, same channels. You keep what you have and stop overpaying for it.
Is it only for low-income seniors?
No. Most moves have no income test. Help that depends on income has its own section, and we never count it in our totals.
Does it work in my province?
Most moves are federal and work in every province. The tax moves (1 to 3) are federal rules; our dollar figures use federal and Ontario tax rates, so yours will differ. Three moves are Ontario programs (hearing aids, the 100-day fill, the drug deductible), each with what BC, Alberta and Quebec offer instead.
Does it work in my state?
Most moves work in every state. Where a rule depends on your state, the move says so and gives you the exact question to ask.
I live alone. Is it still worth it?
Moves 1 to 3 need a spouse, so you start at Move 7. Every Save move shows what it’s worth for one person.
The video was free. Why pay?
The video tells you what exists. The manual gives you the form, the deadline, who to call, the exact words to say, and a page to write down who you spoke to.
Is the price in Canadian dollars?
Yes. C$47 total, tax included. The checkout charges your card in Canadian dollars, so C$47 is exactly what you pay.
I’d rather have it on paper.
Large 18-point print. It prints at home on ordinary letter paper, or at a library. Take the pages to your tax preparer.
What happens after I pay? I’m not good with computers.
A download button right away, and an email with your link. Keep that email. It opens on any phone, tablet or computer; spread two fingers on the screen to make the print bigger. Nothing comes in the mail. Can’t find the email? Look in spam first, then write to [email protected] and a person answers.
Why does the checkout ask for my address?
Card payments need a billing address; it’s a bank rule, and it helps stop card fraud. We don’t mail you anything, and we don’t call you.
Can my wife or husband use it too?
Yes. One purchase covers your household. Many moves work best done together, and the Family Workbook is made to fill in side by side.
Is this financial advice?
No. It’s education: the official rule, the deadline and the free helper for each move. The decision stays yours.
Is it up to date?
Every figure was checked against official sources in October 2026, with the source on the page. The January 2027 update is free.
Will anyone call me or sell me more?
No. One payment. No subscription. No phone calls.
What if it isn’t right for me?
Email us within 30 days for every penny back. No reason needed.
The Home Front Manual · 2026–2027 Edition

One payment. If it isn’t right for you, every penny back.

The Home Front Manual, US Edition. The Home Front Manual, Canadian Edition.
$47 One payment US dollars

You’re ordering the US Edition. You’re ordering the Canadian Edition.

Loading the secure checkout…

Checkout not loading? Pay on the secure Whop page →

Instant access · Pay once · Yours forever

Secure checkout · Visa · Mastercard · Apple Pay · Google Pay · 30-day refund

P.S. The Medicare drug-plan window closes on December 7, and free counselor appointments fill up late in the season. That one move is worth $1,200 a year to our example couple.The hearing-aid rule alone is worth $2,820 on one pair. It’s on page 37.If one of you gets most of the pension, the late split comes first. The CRA’s limit for 2023 is December 31, 2027, the forms go by mail, and the CRA can take up to 35 weeks. Mail by November 30 so all three years’ refunds can arrive within 12 months. The words are on page 28. The CRA decides whether to accept it.If one of you gets most of the pension, the 2023 split must reach the CRA by December 31, 2027. The CRA decides whether to accept it. If it isn’t right for you, you get every penny back.

Ready when you are

After a lifetime of looking after everyone else, take a closer look at what you’ve built.

Get the Manual · $47 →

$47 · If it isn’t right for you, every penny back.